
TIER IV's planned Tokyo Stock Exchange Growth Market listing gives Japan a public-market test of a deep-tech idea that is bigger than one startup: can open-source autonomous-driving software become investable infrastructure?
The Japan Exchange Group's new-listing page, updated July 16, shows TIER IV scheduled to list on July 22, 2026 under code 593A, with an offering price of JPY 1,085. The Tokyo Stock Exchange outline, dated June 29, describes the company as an Information & Communication issuer developing autonomous-driving systems and platforms that leverage Autoware, the open-source autonomous-driving software.
For international readers, the point is not that Japan is suddenly ahead in robotaxis. It is that the TSE is getting a listed vehicle tied directly to software-defined mobility, Level 4 deployment work and an open-source ecosystem that reaches beyond Japan.
Key Takeaways
- TIER IV is scheduled to list on the TSE Growth Market on July 22, 2026; as of this article's July 17 cutoff, it has not yet begun trading.
- JPX shows an offering price of JPY 1,085, at the top of the indicated JPY 1,015 to JPY 1,085 range.
- The public-offering component is 17,449,600 newly issued shares. A simple ATG Press calculation from JPX's share count and offer price implies about JPY 18.93 billion in gross primary proceeds before fees.
- The strategic question is whether Autoware and TIER IV's platform model can convert technical adoption, public-sector projects and global testing into durable commercial revenue.
- No TradingView chart is included because TIER IV has not started trading; using a live chart before the first trading day would risk showing a placeholder or unrelated instrument.
What The TSE Filing Says
The TSE outline is a useful starting point because it separates the listing facts from broader autonomous-driving claims. TIER IV's scheduled listing date is July 22, 2026, the market section is Growth Market, and the security code is 593A. The same outline lists founder and CEO Shinpei Kato as representative and gives the company's business description as autonomous-driving system and platform development using Autoware.
The share-count mechanics matter. The outline says TIER IV had 46,074,490 issued shares as of June 29, and 63,524,090 issued shares at the time of listing, including newly issued shares from the public offering. JPX's updated listing table shows 17,449.6 thousand public-offering shares, 3,968.4 thousand secondary-distribution shares and 3,212.7 thousand shares in over-allotment.
Swipe horizontally to view all columns.
| Listing item | TIER IV detail | Definition | Source and data date |
|---|---|---|---|
| Scheduled listing date | July 22, 2026 | Planned first trading day on TSE Growth Market | JPX new-listing page, updated July 16, 2026 |
| Security code | 593A | TSE code assigned to the issuer | TSE outline, dated June 29, 2026 |
| Industry category | Information & Communication | JPX issuer classification | TSE outline, dated June 29, 2026 |
| Offering price | JPY 1,085 | Price shown after book-building | JPX new-listing page, updated July 16, 2026 |
| Public offering | 17,449,600 shares | Newly issued shares sold through the offering | JPX new-listing page and TSE outline |
| Secondary distribution | 3,968,400 shares | Existing shareholders' shares sold through underwriters | TSE outline, dated June 29, 2026 |
| Over-allotment | 3,212,700 shares | Additional placement size shown by JPX as OA | JPX new-listing page, updated July 16, 2026 |
| Issued shares at listing | 63,524,090 shares | Includes newly issued public-offering shares | TSE outline, dated June 29, 2026 |
Those numbers make this more than a tiny thematic listing. But they do not by themselves prove valuation support. The Growth Market gives investors exposure to earlier-stage companies with higher execution risk than mature Prime Market issuers.
Why The Autoware Angle Matters
TIER IV is not presenting itself as a conventional auto-parts supplier. Its official English site says it builds services and products around Autoware, while the Autoware Foundation describes Autoware as an open-source autonomous-driving project built on Robot Operating System and designed for commercial deployment across a broad range of vehicles and applications.
That open-source base is the article's international angle. Autonomous driving has often been discussed as a race among closed systems backed by automakers, technology giants or robotaxi operators. TIER IV's pitch is different: a shared software stack, implementation services and platforms that let automakers, suppliers, universities and fleet operators build on a common foundation.
The advantage is that an open ecosystem can attract partners and lower switching costs. The risk is that open-source visibility does not automatically create pricing power. Investors will need to watch whether TIER IV can keep enough proprietary value in integration, operations, development tools, data pipelines and safety assurance.
The Capital Market Signal
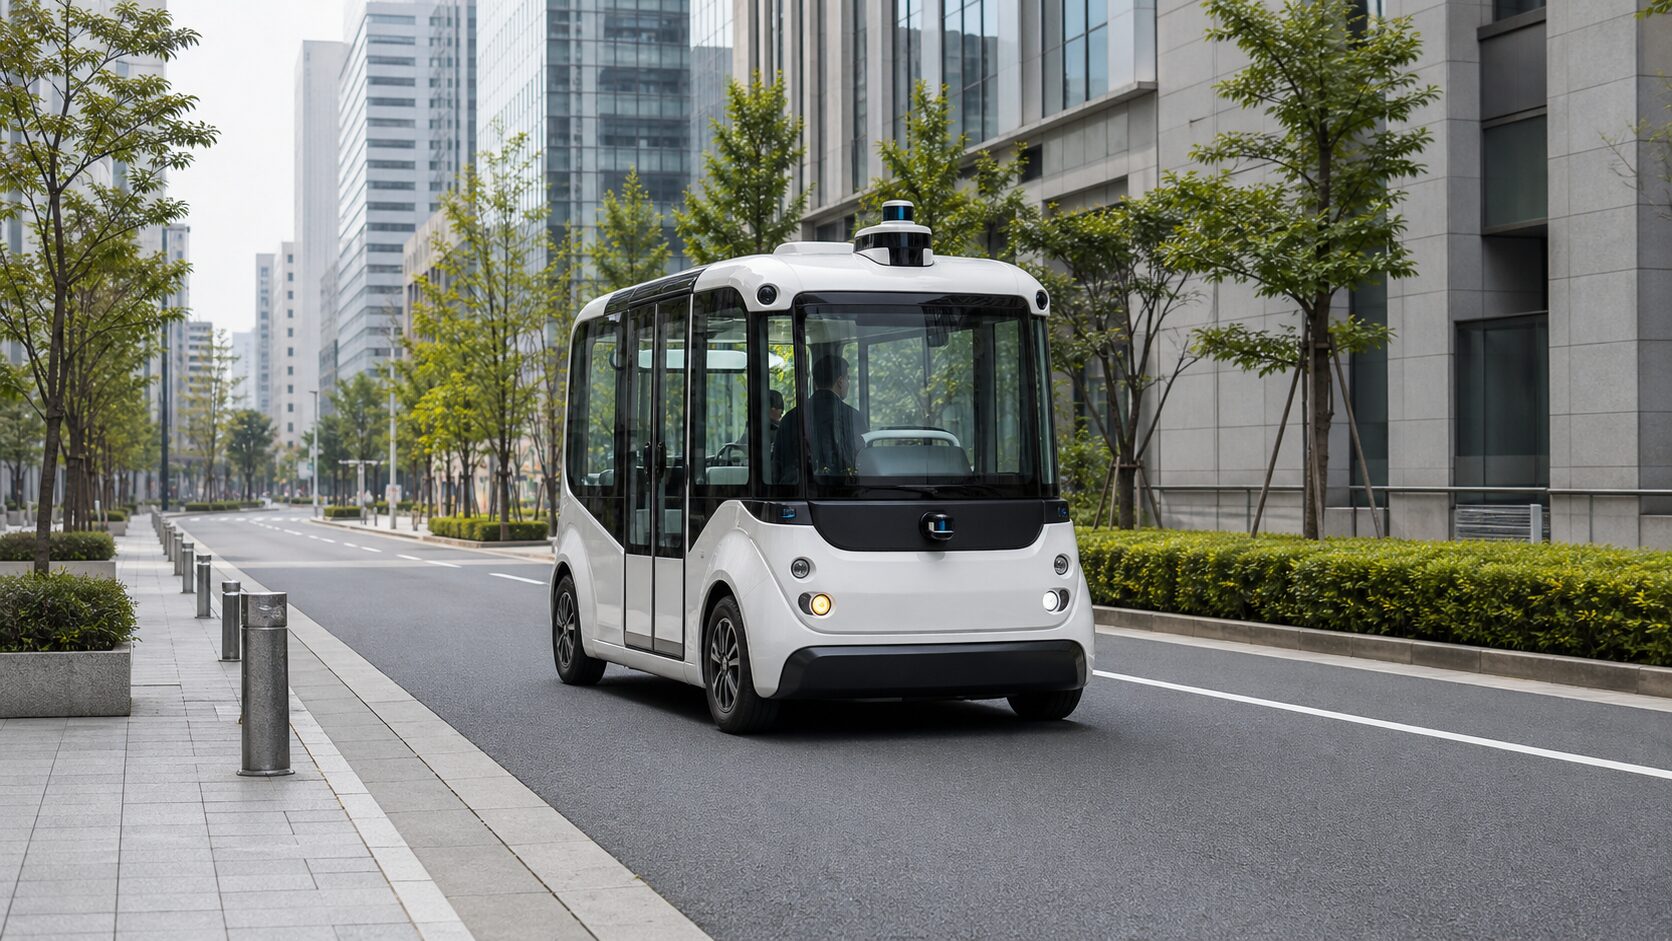
Japan's startup market has often struggled to connect deep technology with public-market scale. A TSE Growth listing by an autonomous-driving software company therefore carries a broader signal: domestic markets are being asked to fund software-defined mobility, not only consumer apps or asset-light internet services.
The timing also fits Japan's policy backdrop. The official RoAD to the L4 project, backed by the Ministry of Economy, Trade and Industry and the Ministry of Land, Infrastructure, Transport and Tourism, describes Level 4 mobility deployment as a way to address mobility issues and promote advanced services. Its project overview says Japan had already initiated Level 4 passenger-transport implementation cases and, from 2026 onward, sought practical implementation of Level 4 autonomous trucking between Tokyo and Nagoya on the Second Tomei Expressway.
Level 4 means automated driving under defined conditions, not everywhere and not in every weather or traffic situation. That distinction matters. The public-market story is not a near-term promise of universal driverless vehicles. It is a bet that constrained routes, shuttles, logistics corridors and specialist operating domains can become commercial markets.
The Commercial Test Is Still Ahead
TIER IV's March 2026 press release says the company developed Level 4 software stacks powered by data-centric AI and made them publicly available through Autoware repositories. It also says TIER IV is testing Level 4 features in Tokyo, Pittsburgh and Munich, using different vehicles and sensor configurations with safety drivers on board according to local regulations.
That is useful evidence of ambition and technical direction. It is not yet evidence of mature public-company economics. The harder questions after listing will be revenue mix, gross margin, customer concentration, safety-case costs, liability allocation and how quickly pilot projects convert into recurring platform or operating revenue.
Swipe horizontally to view all columns.
| Watch item | Why it matters | Evidence to look for | Timing |
|---|---|---|---|
| First trading and liquidity | Shows how public investors price deep-tech execution risk | First-day price formation, volume and lock-up disclosures | From July 22, 2026 |
| Revenue model disclosure | Separates platform economics from one-off engineering work | Future earnings reports and securities filings | After listing and quarterly reporting |
| Level 4 deployment progress | Tests whether pilots become operating services | Public project updates, customer announcements and safety approvals | 2026 onward |
| Overseas validation | Measures whether Autoware-based testing travels across markets | Updates from Tokyo, Pittsburgh and Munich programs | After the March 2026 test announcements |
| Ecosystem strength | Helps assess whether open source becomes distribution or commoditization | Autoware contributors, commercial members and partner deployments | Ongoing |
The most defensible reading is balanced. TIER IV gives investors a cleaner public-market window into Japan's autonomous-driving software stack. It also exposes them to the long commercialization cycle that comes with safety-critical mobility.
What To Watch Next
The first date is July 22, when trading is scheduled to begin. A strong debut would not prove the business model, and a weak debut would not invalidate the technology. It would simply show how investors are pricing liquidity, scarcity and growth risk on day one.
The second checkpoint is the first post-listing disclosure cycle. Investors should look for how management describes contract structure, platform revenue, engineering services, cash use and overseas expansion. If the company can show repeatable customer economics rather than project-by-project development work, the IPO will look less like a theme trade and more like a capital-market bridge for Japanese deep tech.
The third checkpoint is public implementation. Japan's mobility problem is real: aging regions, driver shortages and constrained public transport all create demand for new operating models. TIER IV's listing matters because it asks whether public investors will fund the software layer behind those models before the market is fully proven.
Sources
- Japan Exchange Group: New Listings
- Tokyo Stock Exchange: Outline of Initial Listing Issue for TIER IV
- TIER IV: AI-based Level 4 autonomous-driving press release
- TIER IV English website
- Autoware Foundation
- RoAD to the L4 project
Disclaimer
This article is for informational purposes only and does not constitute investment advice.

